
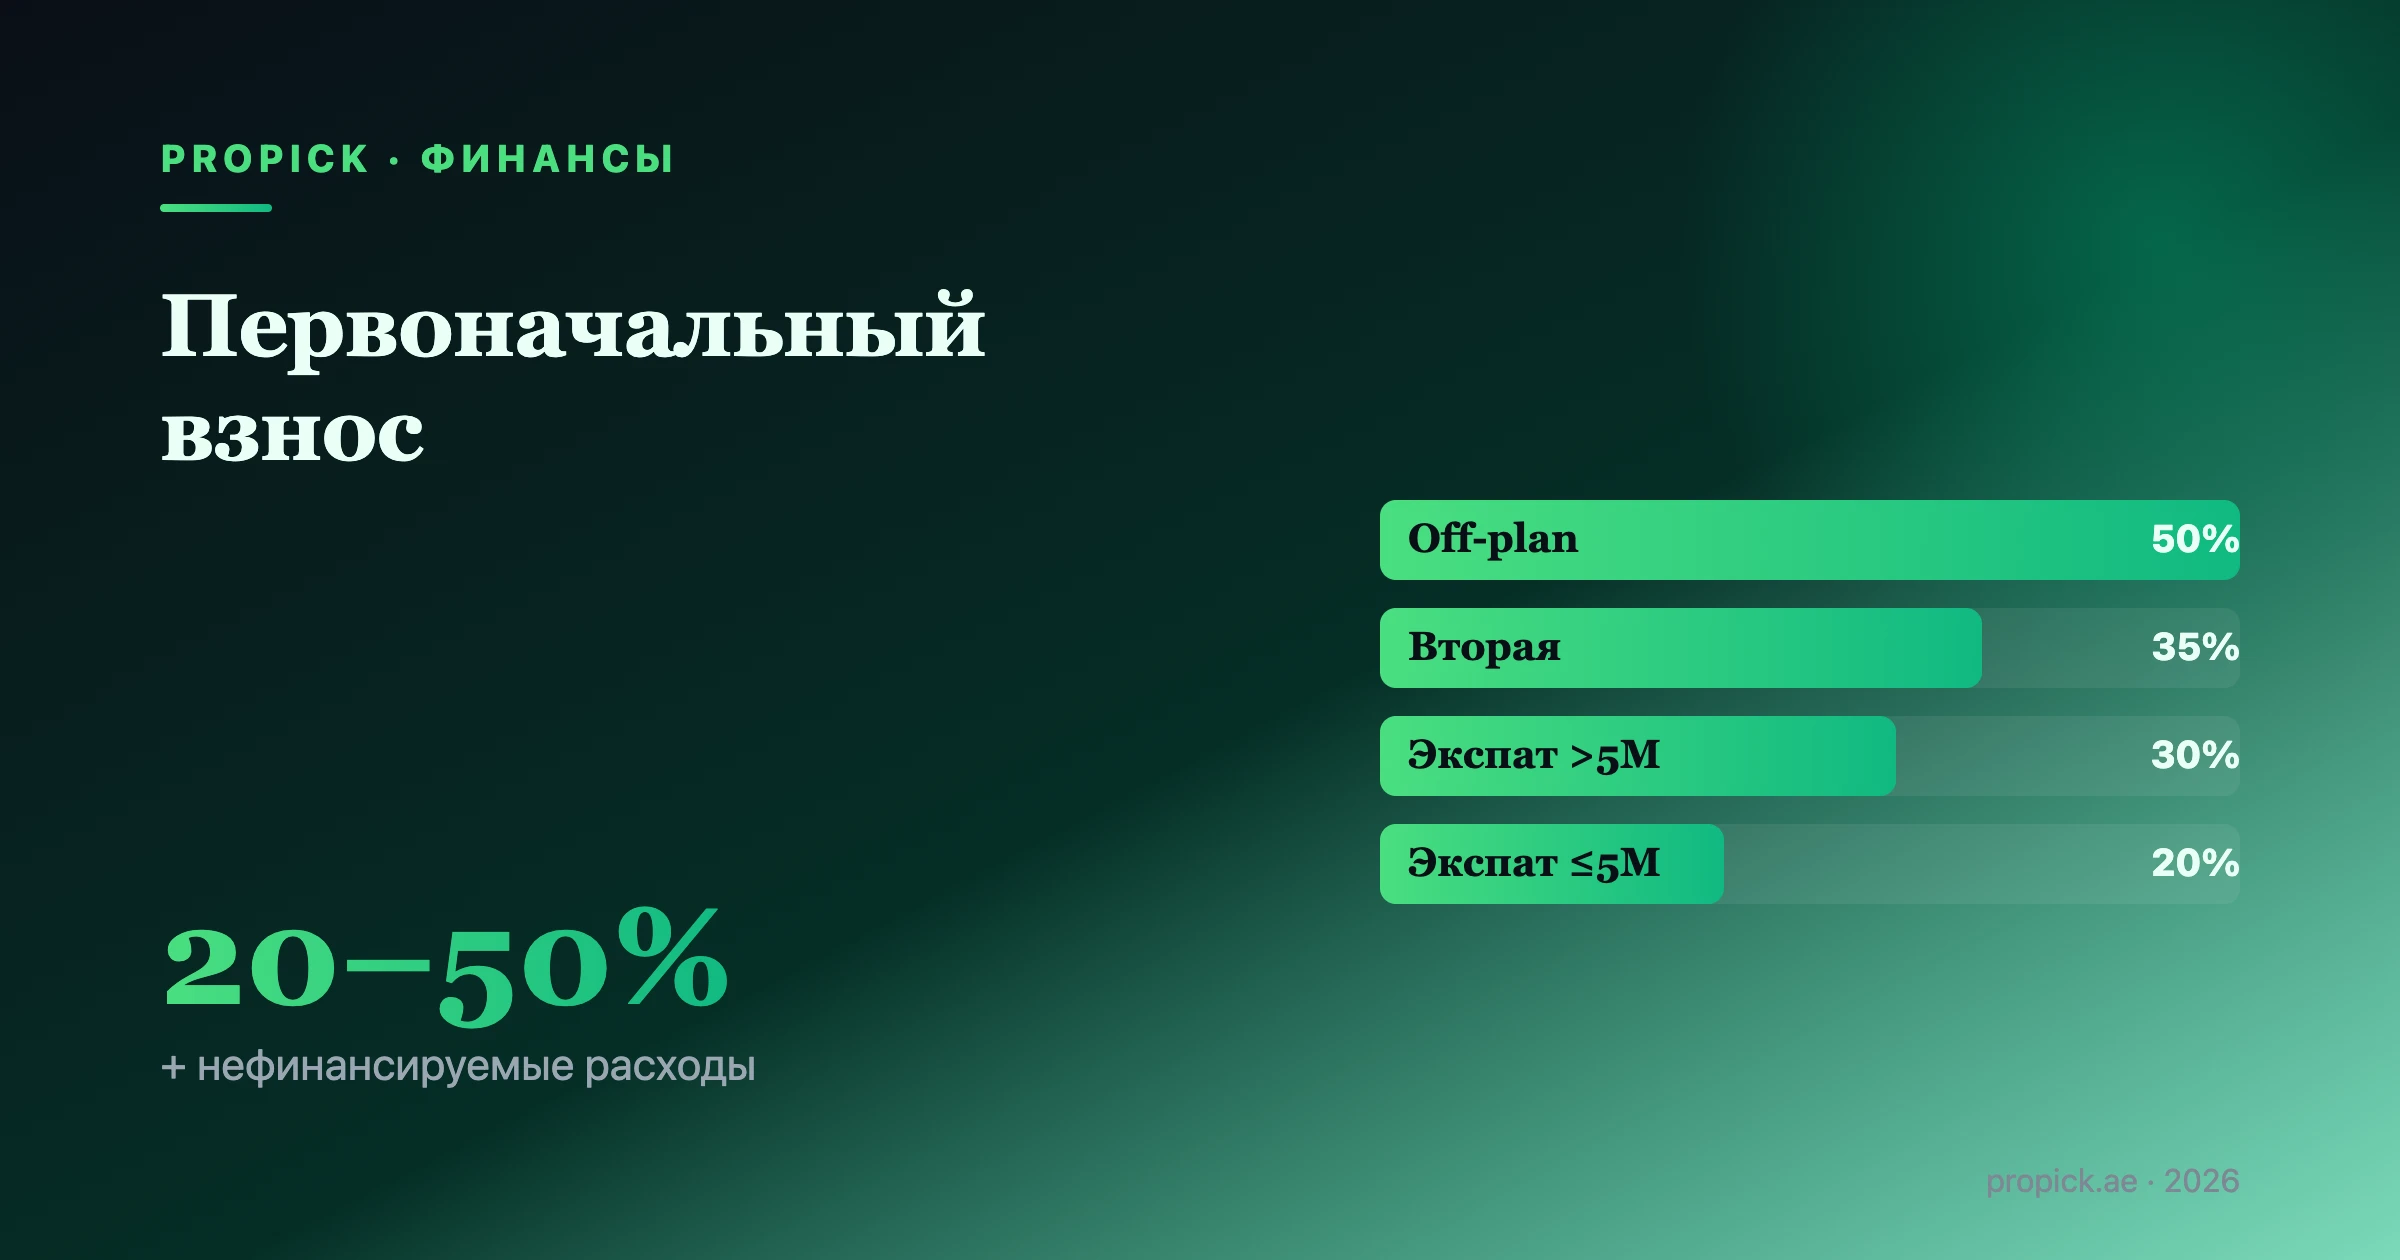
Most buyers arrive in Dubai with one number in their head: 20% down. That figure is roughly right for a mortgage on a first home under AED 5 million, but it leaves out everything else due in cash on signing day, none of which a bank will lend against. Once the transfer fee, trustee charges, agency commission and mortgage paperwork are added up, a buyer financing a modest apartment is often writing a check for close to 28% of the price, not 20%. Cash buyers, still the majority of Dubai's resale market, get a lighter bill, but not a free one.
This guide separates two questions usually bundled together: how much a bank will lend you, and how much cash you need on top of that to get the keys. Every rule is sourced to the regulator or agency that made it, and every AED figure is worked through on real Dubai community prices.
What the Central Bank actually caps
Dubai mortgages are not underwritten purely on a bank's appetite. The Central Bank of the UAE sets hard ceilings on how much of a property's value any licensed lender can finance, through Article 3 of the Regulations Regarding Mortgage Loans, issued as Circular 31/2013 and still in force. The ratios differ by nationality, by whether it is your first home, and by price band:
UAE nationals, first home / owner-occupier (one property per borrower under this category):
- Up to AED 5 million: maximum 85% LTV, so a minimum 15% down payment
- Above AED 5 million: maximum 75% LTV, minimum 25% down
UAE nationals, second home or investment property: maximum 65% LTV regardless of value, minimum 35% down.
Expatriates, first home / owner-occupier (again, one property per borrower under this category):
- Up to AED 5 million: maximum 80% LTV, minimum 20% down payment
- Above AED 5 million: maximum 70% LTV, minimum 30% down
Expatriates, second home or investment property: maximum 60% LTV regardless of value, minimum 40% down.
The same rule caps how much of your income can service the loan: the Debt Burden Ratio (DBR) cannot exceed 50% of gross salary, the maximum loan term is 25 years, and total mortgage financing is capped at eight years of annual income for nationals and seven years for expatriates. None of this is bank policy that varies lender to lender; it is a regulatory floor every UAE bank must respect.
Off-plan resets the whole calculation
If you are buying a unit still under construction, the price band and nationality tables above do not apply the way you'd expect. The Central Bank caps mortgage financing on any off-plan purchase at 50% LTV, "regardless of purpose, value, or category of purchaser". In practice, most off-plan buyers pay the developer directly through a construction-linked payment plan instead, or wait until the project nears handover, when some lenders will finance a resale transfer at the higher ready-property ratios.
The costs a bank will never lend you
This is the part that catches first-time buyers out. A mortgage covers a percentage of the purchase price. It does not cover a single one of the following, and all of them are due in cash, on top of your down payment, at or before transfer.
DLD transfer fee, 4%. Dubai Land Department's own registration fee schedule sets this at 4% of the sale value. On the secondary market, standard practice is that the buyer pays it, because sellers price their net proceeds accordingly and negotiate it into the headline price rather than the fee itself. Budget for the full 4% as a buyer.
Trustee office fee. Every sale is processed through a DLD-licensed Real Estate Registration Trustee office, which charges AED 4,000 plus 5% VAT for properties valued at AED 500,000 or above, or AED 2,000 plus VAT below that threshold.
Agency commission. Standard market practice in Dubai's resale market is a 2% commission plus 5% VAT, paid by the buyer, the seller, or split, depending on what is negotiated in the agreement. This is market convention rather than a fixed government fee: RERA licenses and regulates the brokers who can legally charge a commission, but it does not set the rate itself.
Mortgage registration. If you are financing the purchase, DLD charges a separate fee of 0.25% of the mortgage value to register the bank's charge over the title, plus a trustee processing fee of roughly AED 4,000 plus VAT and a AED 250 title deed charge.
Bank valuation fee. Before releasing a mortgage, lenders commission an independent valuation of the property. This is not DLD-mandated and varies by bank; as one published example, ADCB's schedule of fees lists a valuation fee of AED 3,150 for apartments and villas (AED 5,250 for construction loans), inclusive of 5% VAT. Other banks set their own charge, so confirm the exact figure with your lender before applying.
Title deed and admin fees. A flat AED 250 for the title deed, plus small knowledge and innovation fees (AED 10 each) and a map fee, all charged through the same DLD registration process.
None of these are optional, and none of them are financeable. They are due in cash alongside your down payment.
Real numbers: three Dubai purchases worked through
To make this concrete, here is the actual cash required for an expatriate, first-time buyer, financing a home under AED 5 million at the maximum 80% LTV, using Propick's community price data drawn from DLD transaction records.
JVC studio, AED 610,000 (JVC's ready-resale median runs around AED 13,697 per square meter, the most affordable of Dubai's major communities):
- Down payment (20%): AED 122,000
- DLD transfer fee (4%): AED 24,400
- Trustee fee (sale registration): AED 4,200
- Agency commission (2% + VAT): AED 12,810
- Mortgage registration (0.25% of the AED 488,000 loan) plus trustee/admin fees: roughly AED 5,400
- Bank valuation fee: AED 3,150
- Title deed and misc. fees: roughly AED 520
- Total cash needed: roughly AED 172,480, about 28% of the purchase price, not the 20% the down payment alone suggests.
Dubai Marina 1BR, AED 1,690,000 (Marina's median sits around AED 21,028 per square meter):
- Down payment (20%): AED 338,000
- DLD transfer fee (4%): AED 67,600
- Trustee fee: AED 4,200
- Agency commission (2% + VAT): AED 35,490
- Mortgage registration plus trustee/admin fees: roughly AED 7,600
- Bank valuation fee: AED 3,150
- Title deed and misc. fees: roughly AED 520
- Total cash needed: roughly AED 456,560, about 27% of the purchase price.
Downtown Dubai 2BR, AED 3,450,000, paid in cash (Downtown's median is around AED 26,478 per square meter, with no mortgage in this scenario):
- Full price paid at signing: AED 3,450,000
- DLD transfer fee (4%): AED 138,000
- Trustee fee: AED 4,200
- Agency commission (2% + VAT): AED 72,450
- Title deed and misc. fees: roughly AED 520
- Total cash needed: roughly AED 3,665,200, about 6% above the sticker price, since there is no down payment gap, mortgage registration, or valuation fee to absorb.
The pattern holds across communities and price bands: a mortgaged buyer at the regulatory minimum down payment should plan for roughly 27 to 28% of the purchase price in total cash, not 20%. A cash buyer needs closer to 6% above the price. Propick's data on the community medians used above, along with figures for Palm Jumeirah, Downtown, Dubai Creek Harbour, Dubai Hills, Sobha Hartland, Business Bay and JLT, comes from DLD transaction records via DLD Open Data.
Why most Dubai buyers skip the mortgage entirely
Cash remains the dominant way to buy property in Dubai. Mortgage-backed deals make up a minority of registered sales, and international buyers paying outright are a large part of why. Sellers and developers are used to negotiating with cash buyers, so a financed buyer competing for the same unit needs pre-approval in hand before making an offer, not after.
How to size your own cash-to-close number
Confirm your LTV band from the Central Bank's Article 3 table: nationality, first home vs. investment, and which side of AED 5 million the property sits on. Your down payment is (100% minus your LTV) times the price. Add 4% for the DLD transfer fee, roughly 2.1% for agency commission with VAT, and a few thousand AED for DLD's trustee and title fees. If financing, add 0.25% of the loan for mortgage registration plus a valuation fee and mortgage trustee charge. That total, not the down payment alone, is what needs to be in your account before you make an offer.
FAQ
Is the down payment in Dubai always 20%? No. 20% is the minimum for an expatriate buying their first home under AED 5 million, under the Central Bank's LTV cap. It rises to 30% above AED 5 million, and to 40% for a second property or an investment purchase. UAE nationals get slightly lower minimums (15%, 25% and 35% respectively).
Can I get a Dubai mortgage as a non-resident foreigner? UAE banks do offer mortgages to non-residents, typically at a somewhat lower maximum LTV than residents get, though the Central Bank's caps set the outer ceiling for every lender. Terms and exact ratios vary by bank, so confirm directly rather than assuming resident terms apply.
Who actually pays the 4% DLD transfer fee, buyer or seller? The rate is 4% of the sale value, per DLD's fee schedule. On the secondary market, the near-universal convention is that the buyer pays it, priced into how the deal is negotiated rather than billed separately to the seller.
Is the down payment different for off-plan properties? Yes. The Central Bank caps mortgage LTV on any off-plan purchase at 50% regardless of buyer category, so a financed off-plan buyer needs a much larger down payment than on a ready resale, which is one reason most off-plan buyers pay the developer directly on a payment plan instead.
Does the 2% agency fee apply if I buy directly from a developer? Usually not. Primary market sales are commonly sold without a separate buyer-side agency fee, since the developer's sales team is compensated by the developer. The 2% convention applies to resale transactions through an agent.
What is the biggest gap between what buyers expect and what they actually need? Mortgage registration, trustee and valuation fees. Buyers budget for the down payment and the 4% DLD fee because those are widely quoted, then are caught off guard by the roughly AED 8,000 to 12,000 in extra charges that come with financing.
Sources
- Central Bank of the UAE, Rulebook, Article (3): Important Ratios, Circular 31/2013: https://rulebook.centralbank.ae/en/rulebook/article-3-important-ratios
- Central Bank of the UAE, Rulebook, Regulations Regarding Mortgage Loans (parent section): https://rulebook.centralbank.ae/en/rulebook/regulations-regarding-mortgage-loans
- Dubai Land Department, Property Sale Registration (transfer fee, trustee fee, title deed and map fees): https://dubailand.gov.ae/en/eservices/property-sale-registration/
- Dubai Land Department, Request for Mortgage Registration (0.25% mortgage registration fee): https://dubailand.gov.ae/en/eservices/request-for-mortgage-registration/
- Dubai Land Department, Sale Registration Application Associated with an Initial Mortgage: https://dubailand.gov.ae/en/eservices/a-sale-registration-application-associated-with-an-initial-mortgage/
- Dubai Land Department, Real Estate Activity License (RERA broker licensing framework): https://dubailand.gov.ae/en/eservices/real-estate-activity-license/
- ADCB, Schedule of Fees, Personal Banking (example bank valuation fee): https://www.adcb.com/en/multimedia/sof/cb-sof-current-charges-fees-310525.pdf
- UAE Ministry of Finance, Value Added Tax (5% standard rate): https://mof.gov.ae/vat/
- Dubai Land Department transaction and rent contract records via DLD Open Data, Propick analysis, 2026 (dld_transactions, dld_rent_contracts)

