Dubai's headline price indices tell you the market is up. They do not tell you where. Average it across seventy-plus registered communities and you get a number that flatters some neighborhoods and hides trouble in others. Business Bay resale apartments gained almost 7% in a year. Two kilometers away, Downtown Dubai resale apartments lost more than 3%. Both facts are true. Neither shows up in a citywide average.
Propick pulled ready-resale transactions for nine of Dubai's most-traded communities directly from the Dubai Land Department's open datasets and built a community-by-community, year-on-year comparison on secondary-market deals only, stripped of off-plan noise. As far as we can tell, no other outlet publishes this specific cut: cross-community YoY growth on ready resale, sourced and reproducible from DLD's own transaction records. Here is what a year of resale trading actually did, area by area.
The headline: Business Bay leads, Sobha Hartland lags
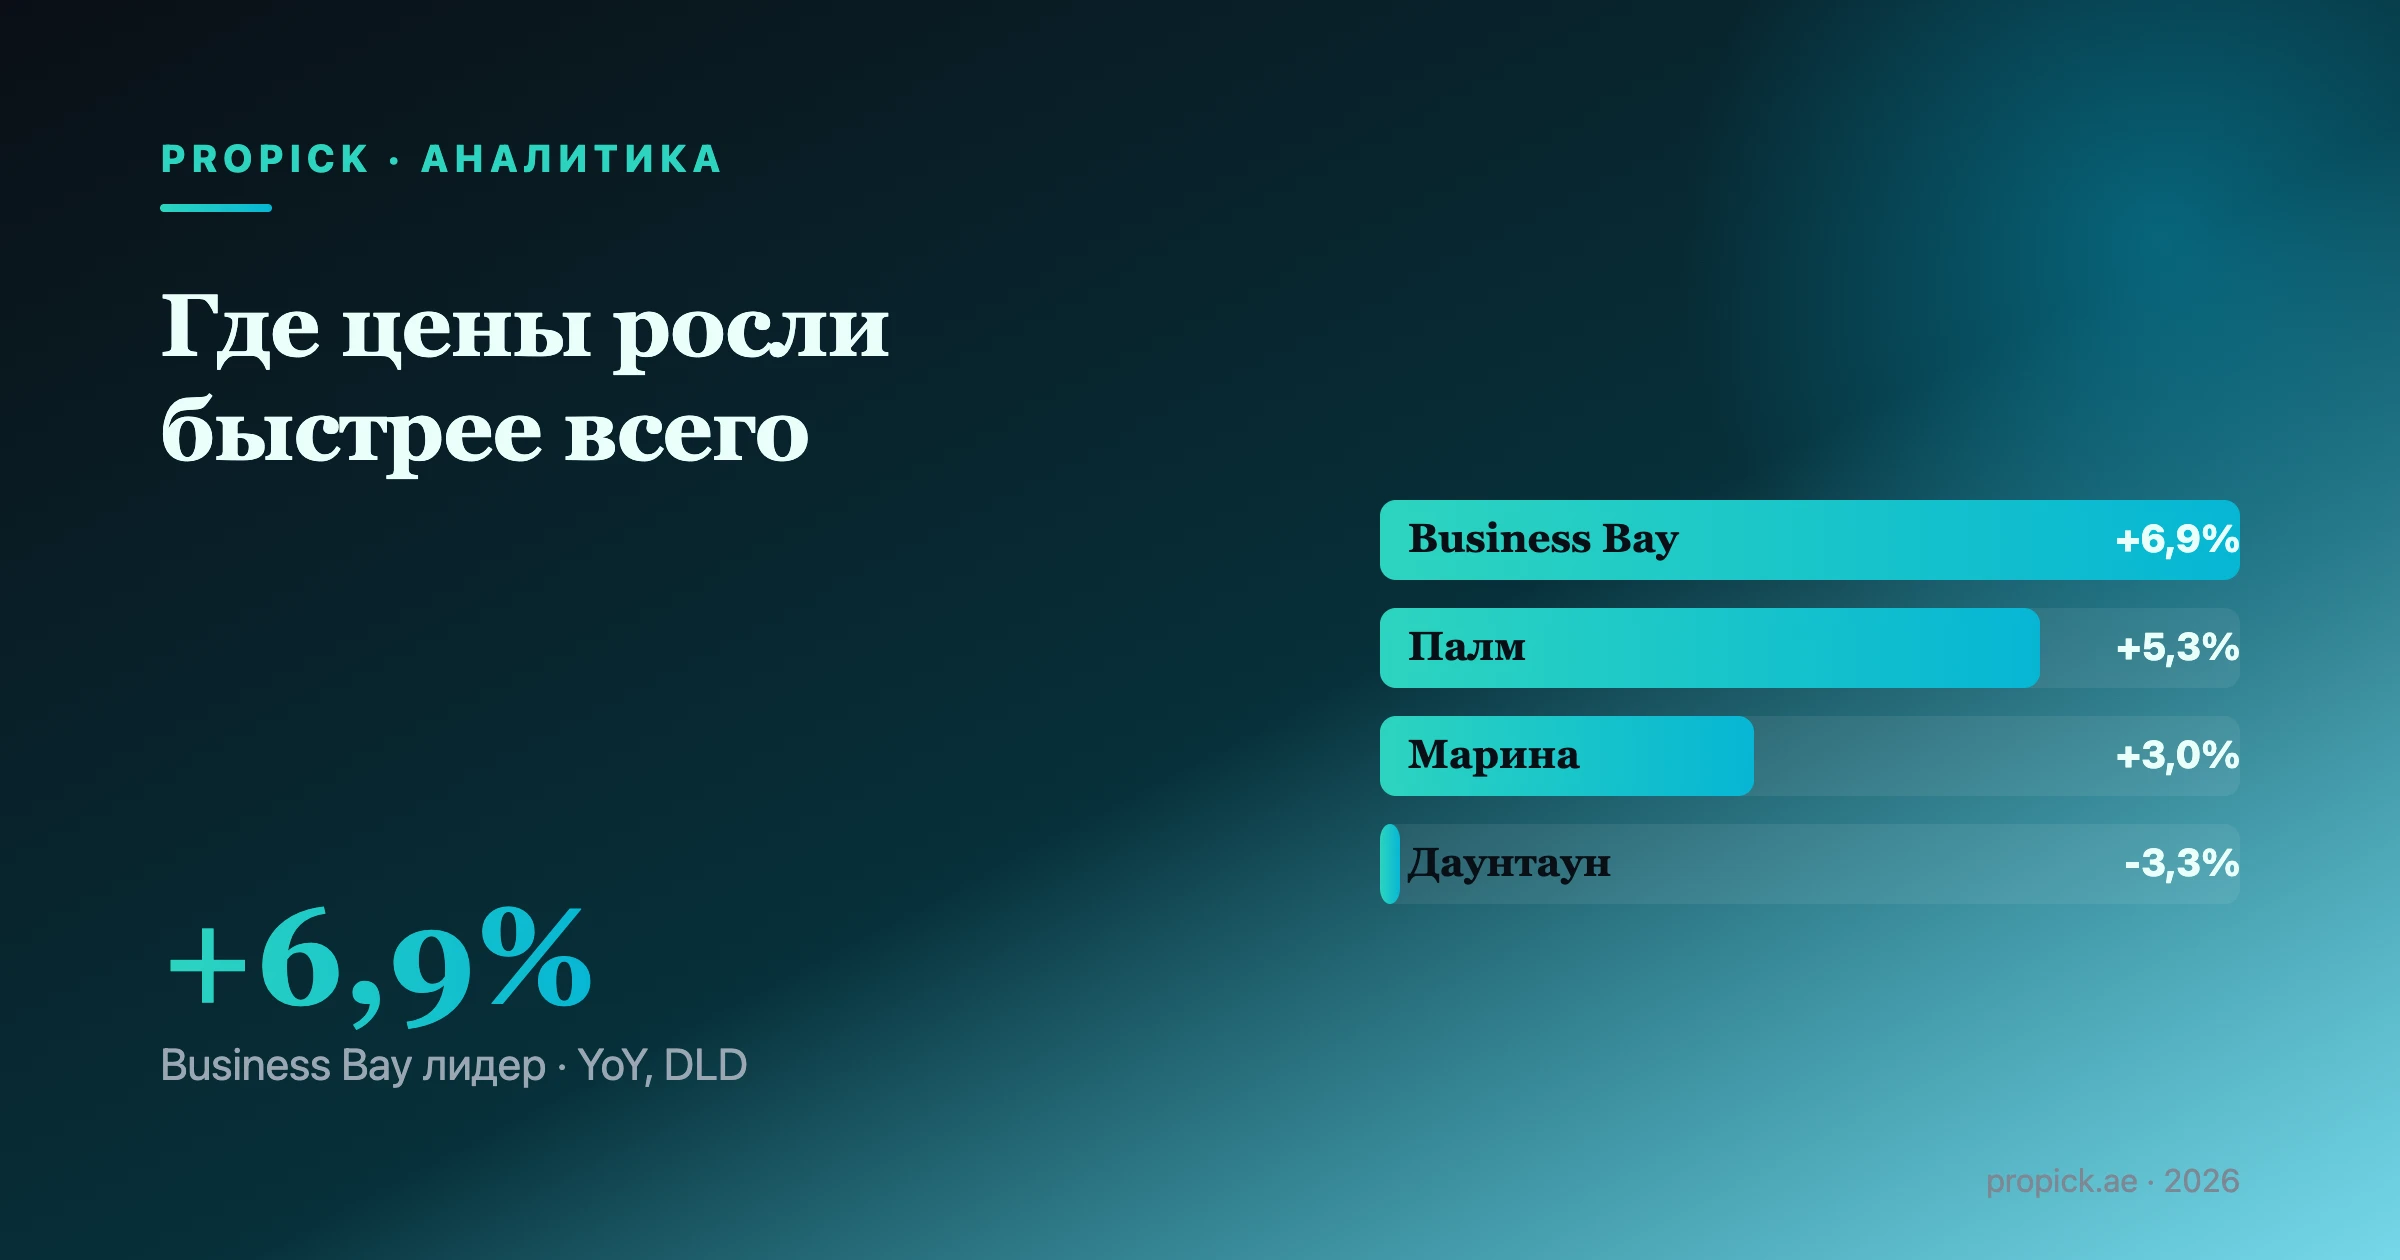
Using median price per square meter on registered ready-resale transactions, here is how the nine communities moved between the twelve months to July 2025 and the twelve months to July 2026.
| Community | 2025 median (AED/sqm) | 2026 median (AED/sqm) | YoY change |
|---|---|---|---|
| Business Bay | 18,998 | 20,306 | +6.9% |
| Palm Jumeirah | 27,562 | 29,036 | +5.3% |
| Dubai Marina | 20,412 | 21,028 | +3.0% |
| Jumeirah Lake Towers (JLT) | 15,290 | 15,666 | +2.5% |
| Dubai Creek Harbour | 24,653 | 25,224 | +2.3% |
| Dubai Hills Estate | 24,693 | 25,022 | +1.3% |
| Jumeirah Village Circle (JVC) | 13,532 | 13,697 | +1.2% |
| Downtown Dubai | 27,381 | 26,478 | -3.3% |
| Sobha Hartland | 22,601 | 21,649 | -4.2% |
Two things stand out immediately. First, the fastest-growing community by far is not one of Dubai's trophy addresses. Business Bay, a mid-market high-rise district squeezed between Downtown and the Creek, outgrew Palm Jumeirah, Dubai Marina and every other community in the sample. Second, the two communities losing value are both established, previously red-hot names: Downtown Dubai and Sobha Hartland. Growth and prestige have decoupled this year.
Why Business Bay is heating up
Business Bay's gain is not a rounding artifact. A move from 18,998 to 20,306 AED/sqm on a resale base this large points to genuine repricing, not a handful of outlier deals. Three forces line up behind it. It sits directly between Downtown and Dubai Marina without carrying either district's premium, which pulls in buyers priced out of both. Metro connectivity along the Business Bay and Financial Centre stations has kept rental demand firm even as new supply landed. And with Downtown cooling (see below), some capital that would have chased a Downtown address a year ago appears to be settling one district over, at a meaningfully lower entry price per square meter.
Palm Jumeirah's +5.3% tells a related but distinct story: constrained land supply on a fixed footprint means new listings cannot dilute pricing the way they can on the mainland, so ordinary demand growth shows up quickly in the resale median.
Why Downtown and Sobha Hartland are cooling
Downtown Dubai remains the most expensive community in this sample at 26,478 AED/sqm, but that median is down 3.3% from a year earlier. Downtown's resale stock has aged past its post-pandemic scarcity phase, and buyers now have credible, cheaper alternatives nearby, Business Bay chief among them, that offer similar access to Dubai Mall and DIFC without the Downtown premium.
Sobha Hartland shows the steepest decline in the sample, down 4.2%. The community is in the middle of an unusually heavy handover cycle: Sobha Realty has flagged a record 6,819 units for handover across its Dubai portfolio in 2026, spanning Sobha Hartland, Sobha Hartland II, Sobha One, Sobha Reserve and Verde (Trade Arabia). When a large volume of freshly completed units enters a resale market at once, existing owners looking to sell typically have to price against new-build competition, which is a textbook mechanism for softening the secondary market even while the broader area narrative stays positive.
Price level versus rental yield: the fuller picture
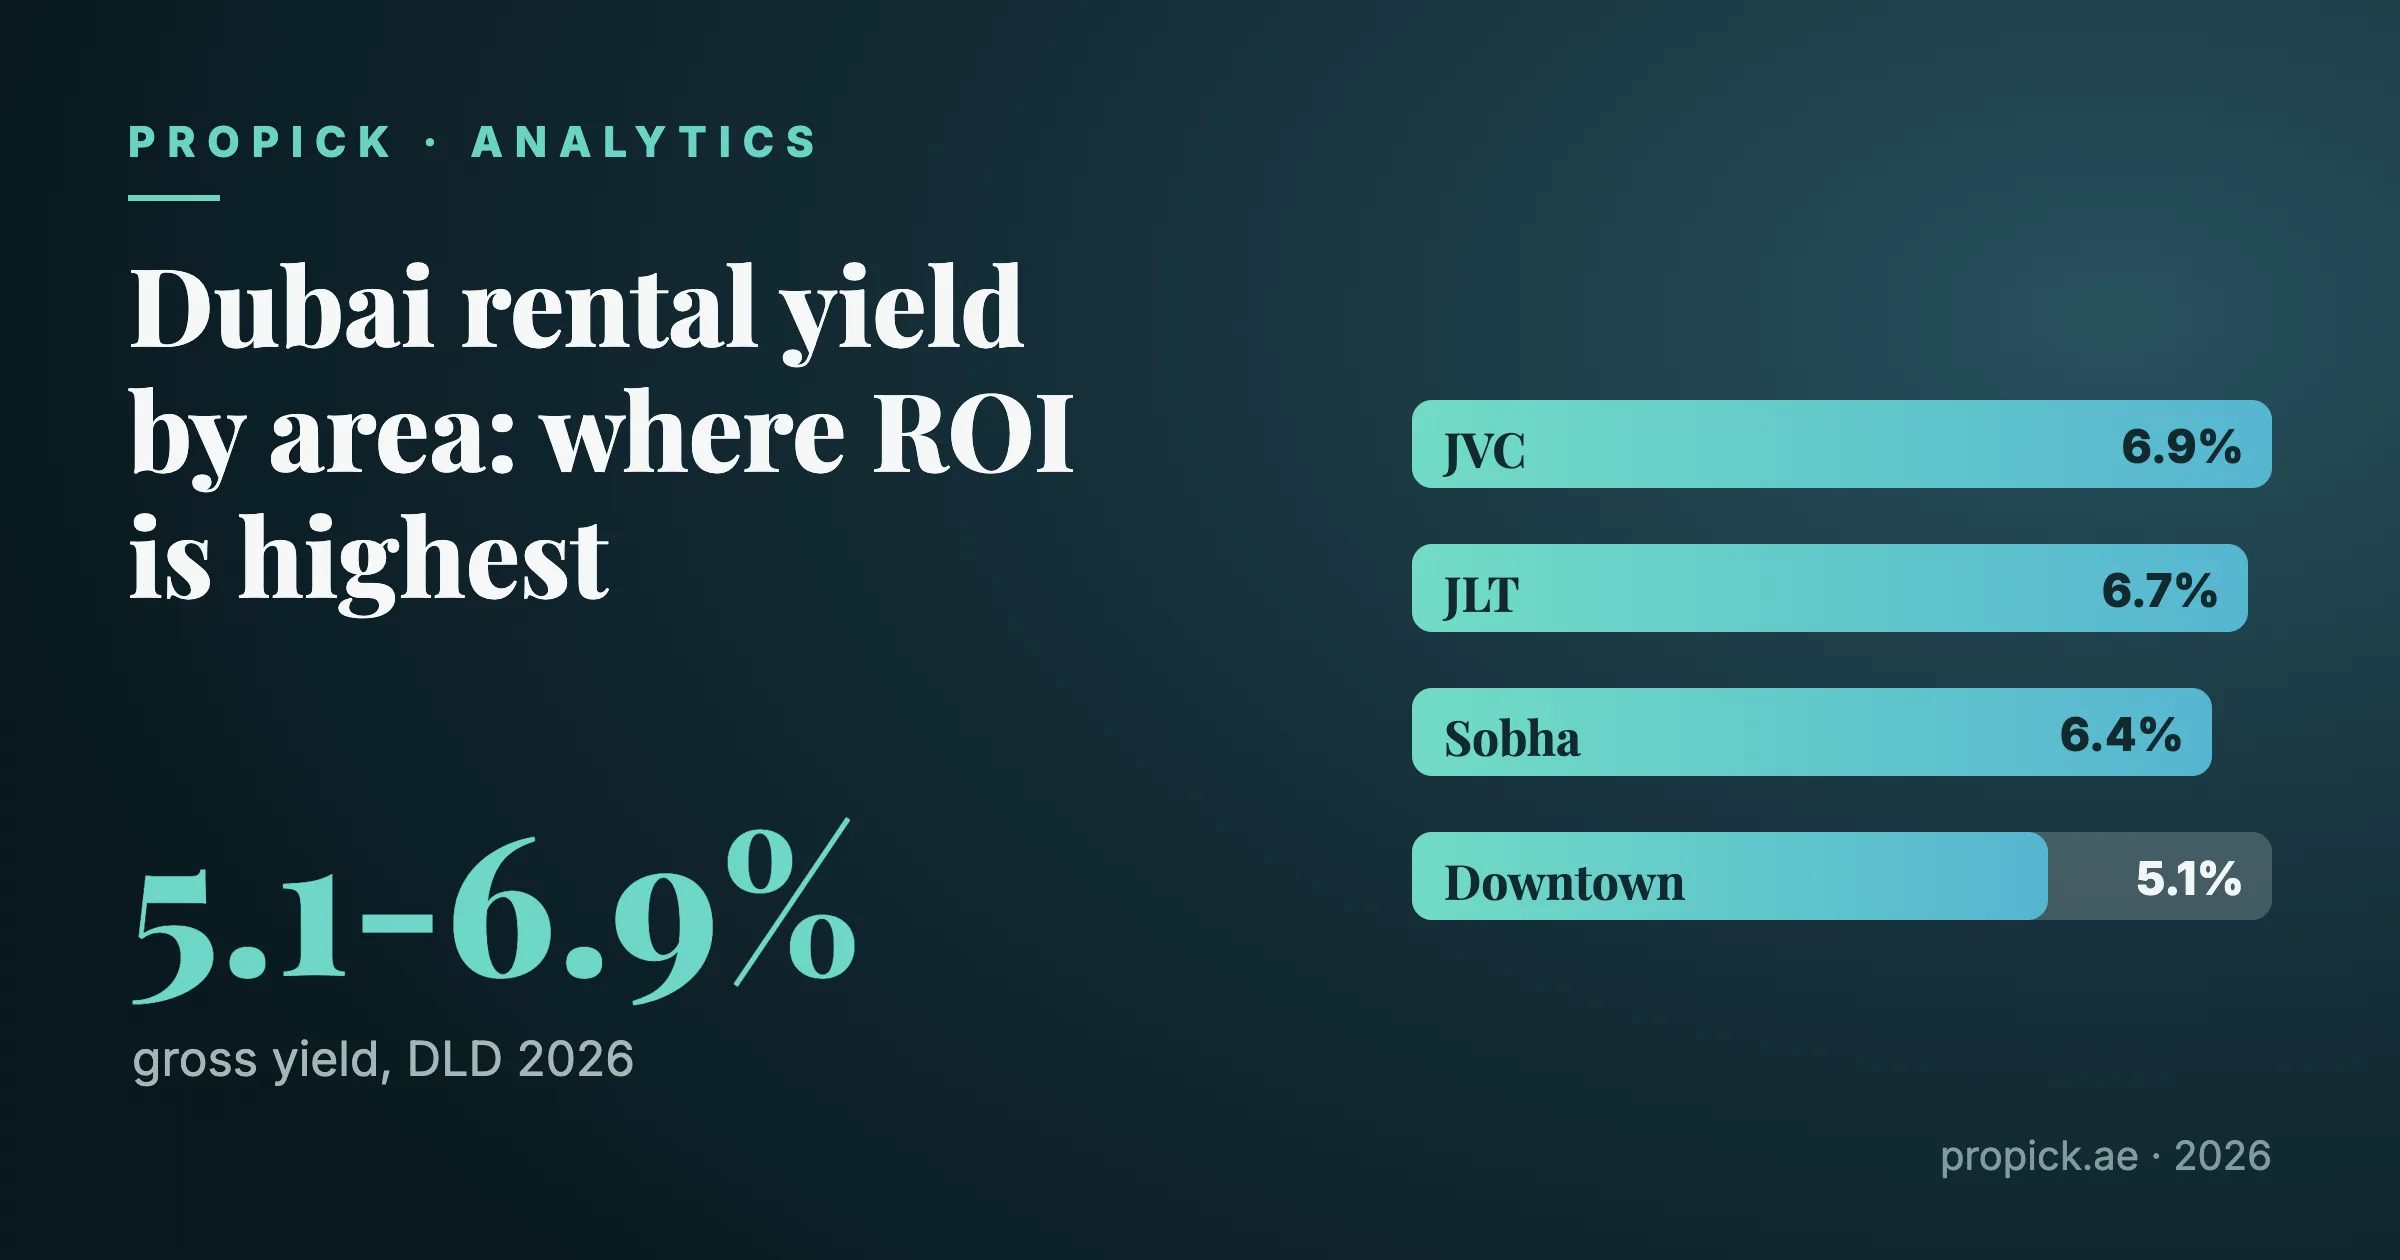
Price growth alone can mislead if you ignore what a unit still yields in rent. Pairing each community's July 2026 resale median with its median gross rental yield (computed from DLD rent-contract registrations against the same resale price base) shows an almost perfectly inverse relationship between price and yield across this sample.
| Community | 2026 median price (AED/sqm) | Gross rental yield |
|---|---|---|
| Palm Jumeirah | 29,036 | 5.4% |
| Downtown Dubai | 26,478 | 5.1% |
| Dubai Creek Harbour | 25,224 | 5.4% |
| Dubai Hills Estate | 25,022 | 6.1% |
| Sobha Hartland | 21,649 | 6.4% |
| Dubai Marina | 21,028 | 5.2% |
| Business Bay | 20,306 | 5.9% |
| JLT | 15,666 | 6.7% |
| JVC | 13,697 | 6.9% |
The two cheapest communities in the sample, JVC and JLT, post the two highest yields, near 7%. Downtown, the most expensive, posts the lowest, near 5%. Business Bay sits in an unusually attractive middle: a yield of 5.9%, better than Downtown or Marina, on a community that is also the fastest appreciating in the sample. Sobha Hartland's falling price has pushed its yield up to 6.4%, which may be exactly why its resale volumes have reportedly held up even as its price median softened: income-focused buyers are stepping in where capital-appreciation buyers are stepping back.
For anyone transacting on this data: on Dubai's secondary market, the Dubai Land Department's 4% transfer fee is, in practice, paid by the buyer, not split between the two parties as the DLD fee schedule nominally allows. That cost sits on top of every price per square meter quoted above and should be built into any yield or return calculation before comparing communities.
Methodology
This ranking is built entirely from Dubai Land Department open data, accessed via the DLD Open Data / data.dubai portal, specifically the dld_transactions dataset (registered sale transactions) and dld_rent_contracts dataset (registered tenancy contracts), cross-referenced against DLD's area and project lookup tables.
We isolated transactions flagged as ready-property resale, excluding off-plan (Oqood) sales and gifts, and grouped units by master_project, matching DLD's own community naming, so that towers and sub-clusters belonging to the same master community (for example, the various Business Bay towers, or Sobha Hartland's phases) are counted together rather than fragmented into dozens of micro-samples. Figures are median transaction price per square meter of gross floor area, chosen over a mean to reduce distortion from a small number of very large or very small units, calculated over rolling twelve-month windows ending July 2025 and July 2026 respectively. Rental yields are gross annual rent (median registered dld_rent_contracts value for the same master project) divided by the 2026 resale median price. Communities included in this sample carry a large enough resale transaction count in both twelve-month windows to support a stable median; thinner-volume communities were excluded rather than published with unreliable figures. Data is as of July 2026 and will shift as DLD updates its public registers; we intend to refresh this comparison periodically.
FAQ
Why did Business Bay grow faster than Downtown or Palm Jumeirah in 2026? Business Bay's resale median rose 6.9% year-on-year, the fastest of any community in this sample, likely reflecting demand spillover from pricier neighbors, solid metro-linked rental demand, and a lower entry price than Downtown or the Marina for comparable central-Dubai access.
Is Downtown Dubai a bad investment now that prices have fallen 3.3%? Not necessarily. Downtown remains the highest-priced community in the sample and its yield, at 5.1%, is stable. A 3.3% pullback after a long run-up looks more like a normalization than a structural decline, but buyers should price in the competition Downtown now faces from Business Bay and other central districts.
Why is Sobha Hartland cooling while other Sobha-branded projects still market strongly? The 4.2% resale decline coincides with an unusually large handover wave, Sobha Realty has flagged over 6,800 unit handovers across its Dubai portfolio for 2026, which puts fresh completed stock in direct competition with existing resale listings in the same community.
Are these figures for off-plan or ready properties? Ready-resale only. Off-plan (Oqood) transactions were deliberately excluded because off-plan pricing is driven by developer payment plans and launch incentives rather than open-market resale conditions, and mixing the two would distort the year-on-year comparison.
What is a master_project grouping and why does it matter? DLD registers transactions at the building or sub-plot level. Grouping by master_project rolls those up to the community level buyers actually search by, for example combining every registered Business Bay tower into one Business Bay figure, so the comparison matches how investors think about location rather than how the land registry files paperwork.
Does the DLD 4% transfer fee affect these price figures? No, the reported prices are pure transaction values from DLD's registry. The 4% DLD transfer fee is a separate closing cost layered on top of the purchase price, and on secondary-market deals in Dubai it is, in practice, paid by the buyer even though DLD's fee schedule nominally allows a 2/2 split between buyer and seller.
Sources
- Dubai Land Department, dld_transactions open dataset, on the Dubai Data and Statistics portal (formerly DLD Open Data): data.dubai
- Dubai Land Department, dld_rent_contracts and related registration datasets, on the Dubai Data and Statistics portal (formerly DLD Open Data): data.dubai
- Dubai Land Department, DLD Residential Sale Index dataset, on the Dubai Data and Statistics portal (formerly DLD Open Data): data.dubai
- Dubai Land Department, property registration and transfer fee schedule: dubailand.gov.ae
- Trade Arabia, "Sobha Realty plans record handover of 6,819 units in 2026": tradearabia.com
All price and yield figures in this article are Propick's own computation from the DLD datasets listed above and have not been published in this cross-community, ready-resale form by any other outlet at the time of writing.